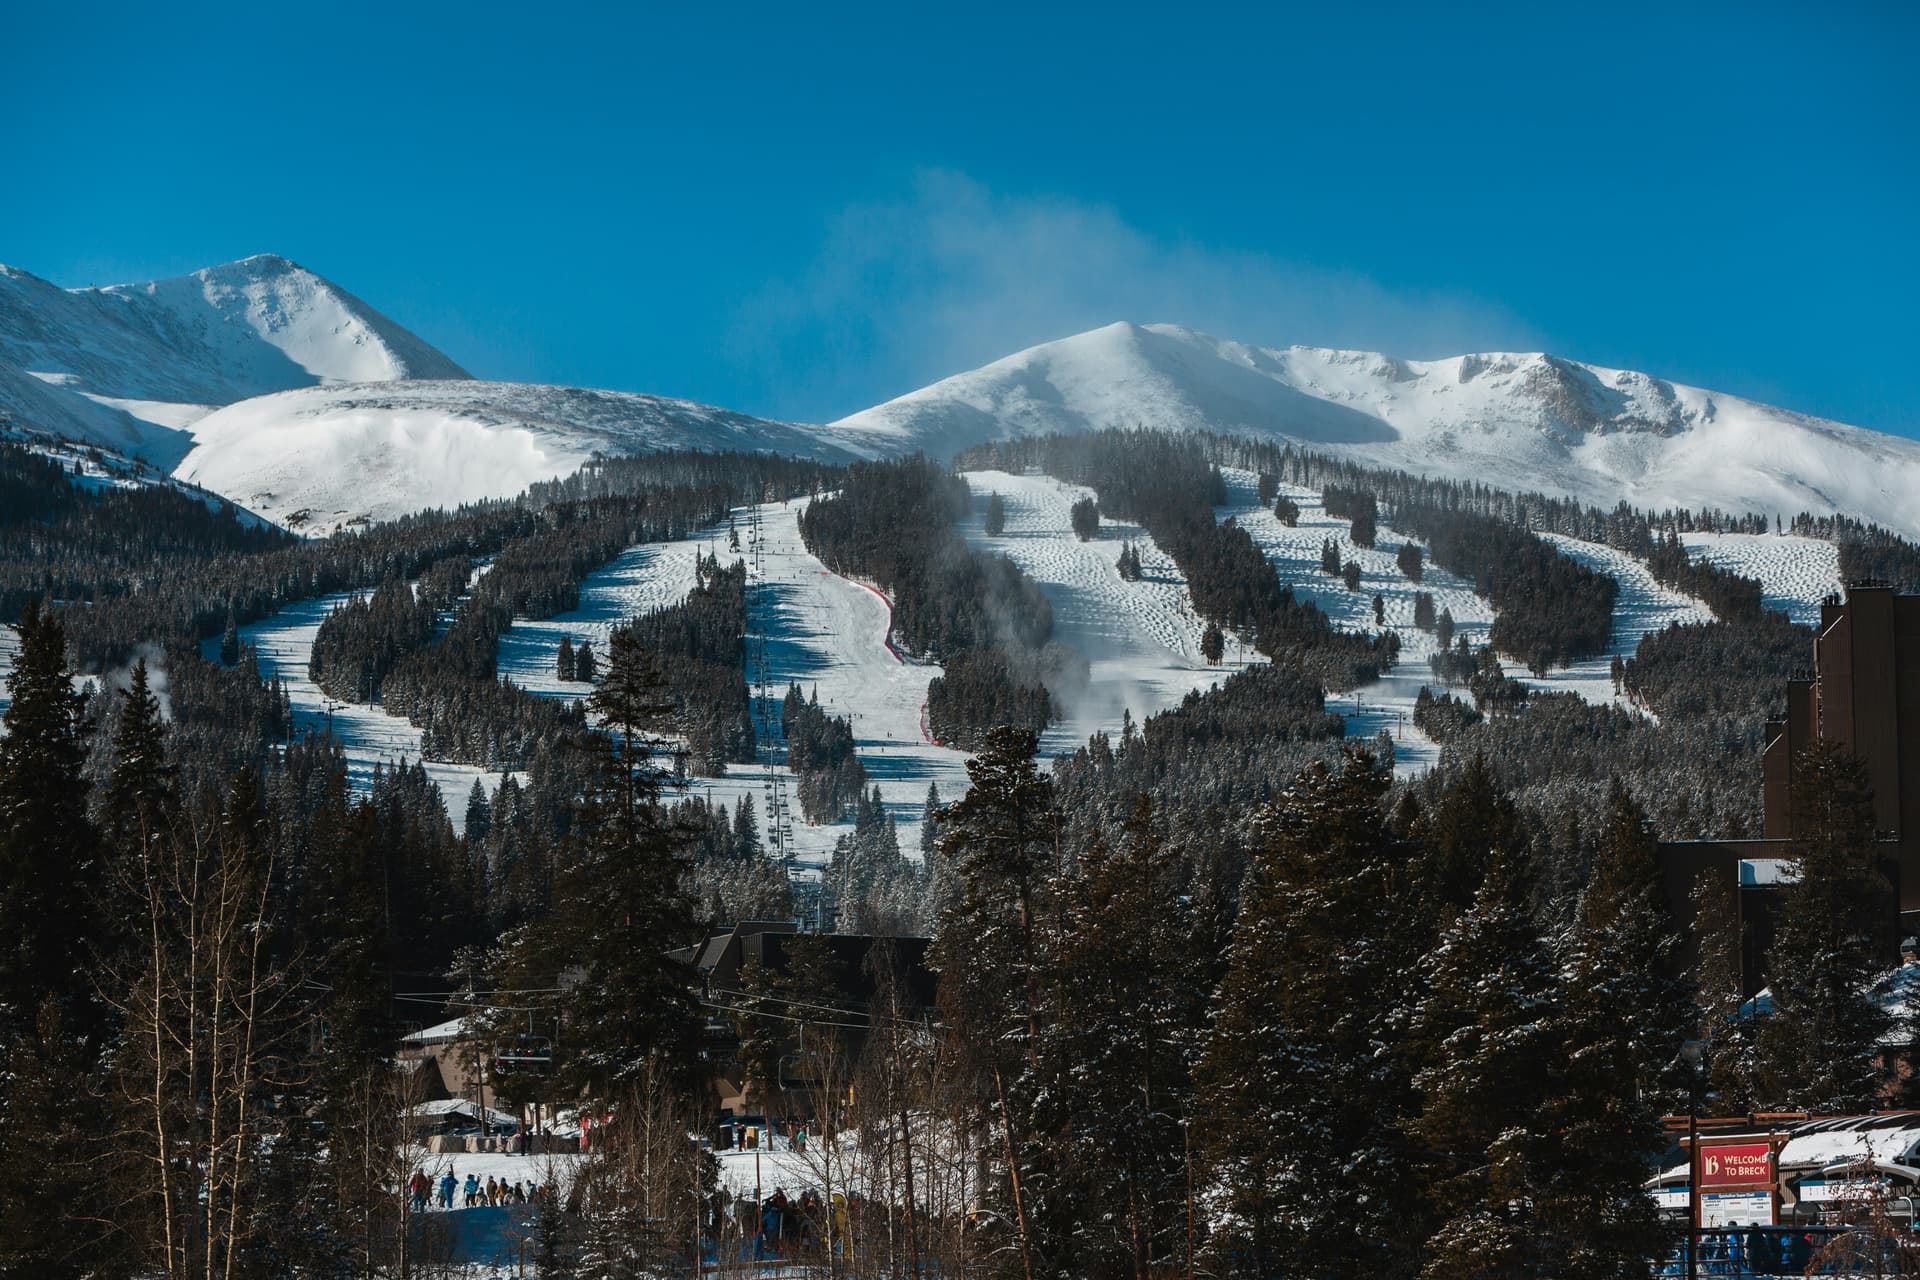
Breckenridge · Summit County
Finance a Breckenridge ski condo or rental
Loans for Breckenridge investment properties and vacation rentals, including resort condos many lenders won't finance.
- 4.9 from 60+ Google reviews
- $1B+ funded
- 30+ years of experience
Why investors work with us in Breck
The hard part in Breckenridge is usually the building, not the borrower.
Non-warrantable condos
DSCR on rental income
LLC vesting
Mountain experience
Financing Breckenridge properties
Breckenridge's historic downtown, skiing and summer events bring visitors in both seasons, which is why it's one of Colorado's most sought-after rental markets.
The main financing challenge is condo warrantability. Many investment condos are in projects with high investor concentration, rental pools or commercial zoning, which makes them non-warrantable for Fannie Mae and Freddie Mac. Large banks and credit unions often can't finance them.
Portfolio lenders and DSCR programs fill that gap. A DSCR loan qualifies on the property's rent instead of your personal income, so the unit's numbers matter more than your tax returns.
Check the short-term rental license first
Breckenridge areas
- Peak 7 / Ski Hill
- Ski-in/ski-out condos and residences
- Downtown / Main Street
- Walk-to-lift condos near shops and restaurants
- Peak 8 base area
- Resort condos, some with hotel-style management
- Warriors Mark / Shock Hill
- Single-family homes near the slopes and gondola
- Four O'Clock Run
- Ski-access condos and townhomes
- Blue River / Spruce Valley
- Homes and townhomes just south of town
Breckenridge investment property questions

Yes. We finance Breckenridge condos as second homes, investment properties and with DSCR loans. Many Breckenridge condo projects have warrantability issues because of high rental concentration, so we work with portfolio lenders and DSCR programs that lend in those projects. Send us the address and we'll check which lenders will finance that building.
It varies widely by unit size, location, amenities, management and licensing. Ski season (roughly December–March) and summer drive most bookings. For a specific property, look at its actual booking history or a current short-term rental data report — lenders will do the same.
Breckenridge requires a short-term rental license and limits the number of licenses in many residential areas, while some resort-zoned properties are treated differently. Whether a license transfers with a sale depends on the town's current rules. Verify the license status of a specific property with the Town of Breckenridge before you make an offer.
Investment condos typically need 15–25% down on conventional loans and 20–25% or more on DSCR loans. Non-warrantable condos through portfolio lenders often need 25–30%. If you'll use the home personally part of the year and it isn't primarily a rental, a second-home loan allows as little as 10% down, but rental income can't be used to qualify. Summit County's 2026 conforming limit is $1,092,500; loans above that are jumbo.
Breckenridge has a walkable downtown, extensive terrain and a year-round events calendar, but entry prices are also among the highest in Summit County. Some investors compare it with Keystone, Frisco or Silverthorne. The right market depends on your budget, how you'll use the property and the numbers on the specific unit.
Yes. Most DSCR lenders allow vesting in an LLC, and many let you form it right before closing. A personal guarantee is usually required. Some portfolio lenders also allow entity ownership on other products.

Ready to invest in Breckenridge?
Get pre-approved, or call Andrew with the building name and he'll tell you which lenders will finance it.