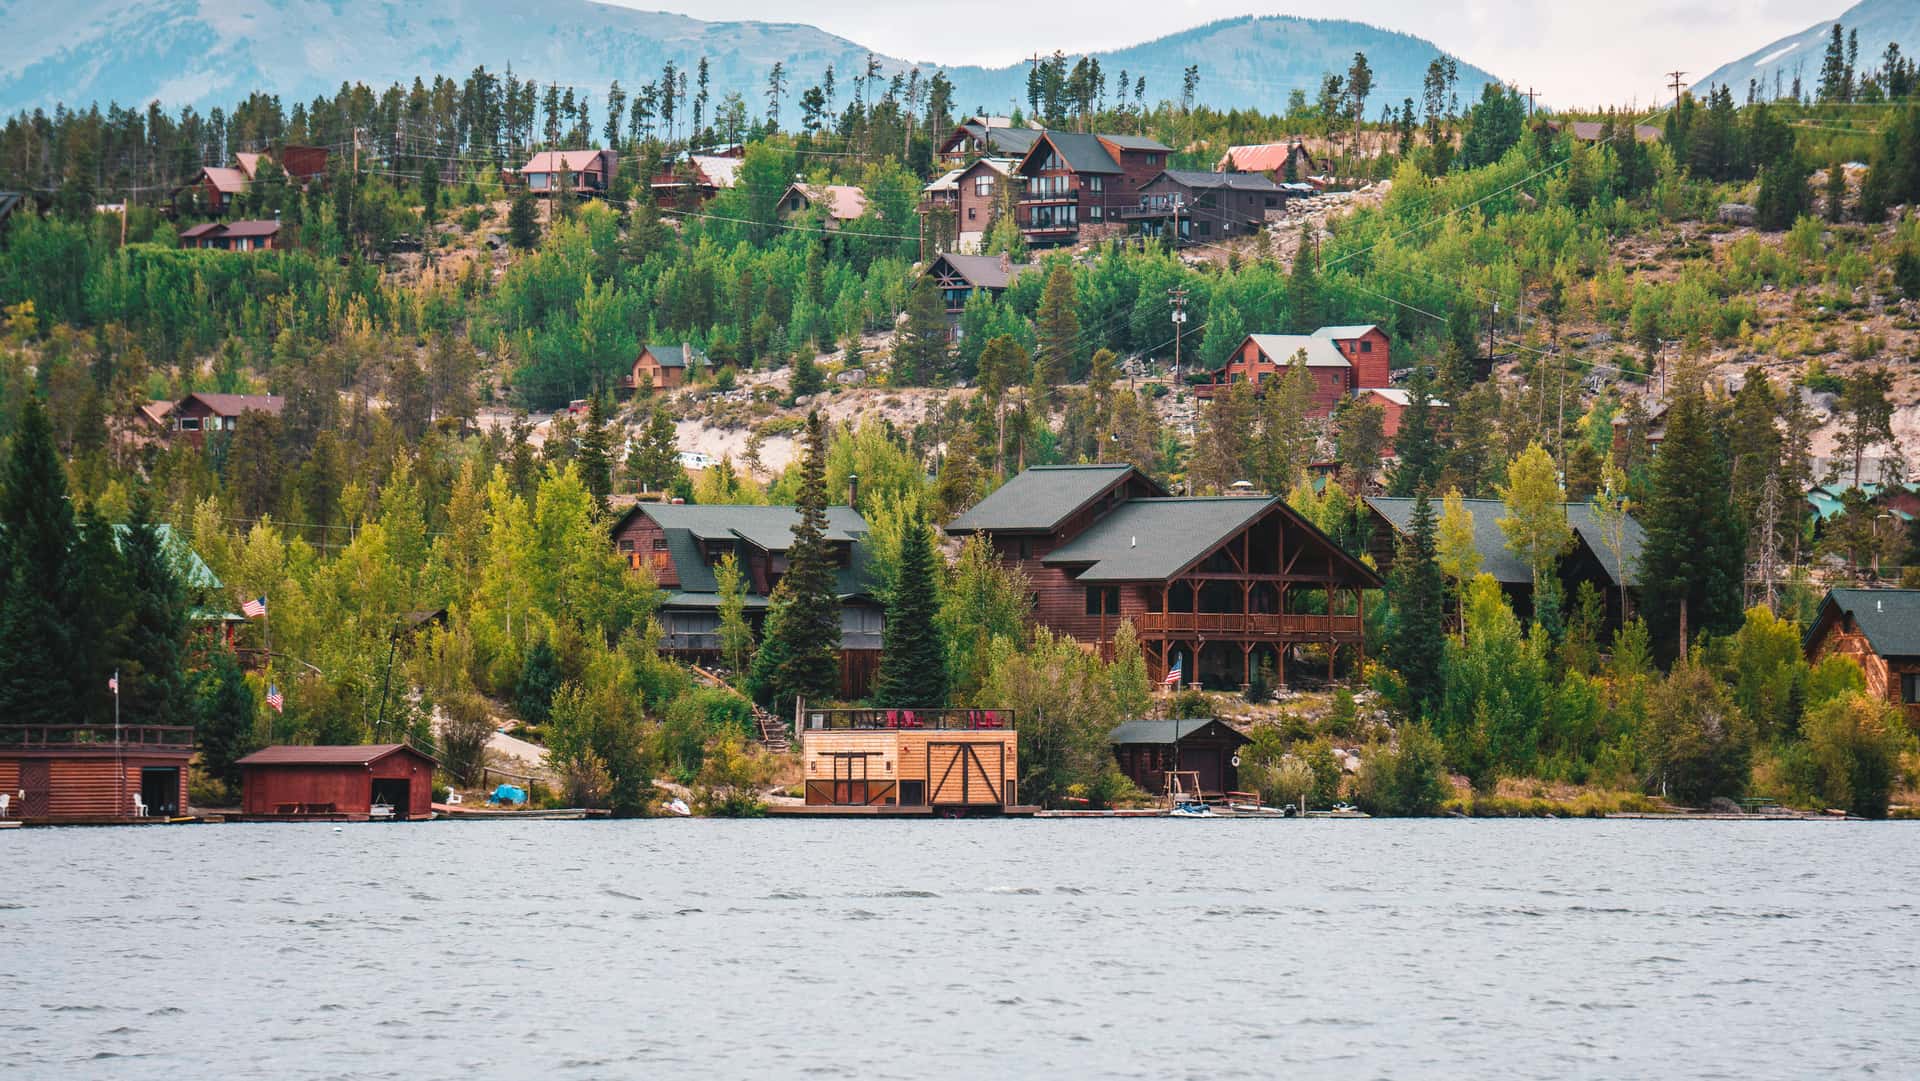
Three Mountains, Three Different 2026s
"Colorado mountain market" is not a single thing. Aspen, Vail, and Telluride are all premium markets, all dependent on second-home and ultra-luxury demand, and all going through different stories right now. If you're buying in any of them, your financing strategy needs to match the specific market, not the headline.
Here's what the data actually shows as of spring 2026.
Aspen: Quiet Top, Constrained Inventory
The Aspen Times reported that Aspen Snowmass first-quarter 2026 sales were the lowest since 2020. Volume dropped sharply. The reason isn't a lack of buyers — it's a lack of inventory at the top.
Inventory in the Aspen core sits roughly 40% below pre-pandemic levels. Average sale prices in the core climbed from about $6.3 million in 2024 to roughly $8.5 million in 2025. The result is fewer transactions at higher prices — a constrained, top-heavy market.
What this means for buyers:
- Patience matters more than speed. Inventory turns over slowly
- Off-market and pocket listings are a bigger share of real opportunities
- Financing readiness is your competitive edge — when the right property shows up, a strong, pre-underwritten file beats a slightly higher offer that needs to be qualified
For Aspen-specific market notes, see our Aspen mortgage page.
Vail: A Tale of Two Price Points
Vail's 2025–2026 market split clearly along price tier. Single-family and duplex sales above $3 million held up well — buyers at that level kept moving. Condos and townhomes under $2 million slowed after the sellout of several major new developments.
That's not a Vail-wide weakness. It's a structural pause. There's less new inventory in the entry-level mountain price band right now, and the buyers chasing that segment are competing harder when something does list.
For Vail buyers, the practical takeaways:
If You're Targeting $3M+
The market is functional. You'll find properties, sellers will negotiate, and inspections matter again. Jumbo financing is competitive. Look at jumbo loan options for high-cost Colorado counties, where the 2026 conforming limit goes up to $1,249,125 — meaning some loans that historically were jumbo now fit inside conforming pricing.
If You're Targeting Sub-$2M Condos
Be ready to compete. Condotel-eligibility, master insurance policy, and HOA reserves will matter for financing more than they would in a stronger condo segment. See Vail second home loans for how condo and second-home financing actually works in Eagle County.
Telluride: Still Climbing at the Top
Telluride posted $868 million in real estate sales across 448 transactions in 2025 — close to 2023 volumes and a sign that the market kept absorbing premium inventory even after the post-pandemic peak. Luxury and ultra-luxury continue to dominate dollar volume.
Two specific projects matter for buyers right now. The Four Seasons Residences Telluride and Highline in Mountain Village both represent significant new luxury inventory. That's good news if you're hunting at the top — there's actual product to look at.
The financing story in Telluride splits along similar lines as Vail:
- Above $3M, jumbo + portfolio financing is the play
- Between $1.25M and $3M, conforming/high-balance pricing may apply depending on county
- Below $1.25M, inventory is the bigger challenge, not the financing
See our Telluride mortgage page for how San Miguel County financing works.
The Financing Toolkit for Mountain Buyers in 2026
Conforming High-Balance
In Eagle, Pitkin, San Miguel, Routt, and Summit counties, conforming loan limits in 2026 go up to $1,249,125. That means a meaningful number of "jumbo by feel" purchases actually fit inside Fannie Mae or Freddie Mac pricing. Always check the county limit first before assuming you need a jumbo product.
Jumbo Loans for Second Homes
Many mountain buyers want a second home with 10% to 20% down. There are jumbo programs that work for that — including 10% down for strong-credit second-home borrowers — and pricing has tightened against conforming in 2026.
Asset Depletion
For buyers with significant assets but modest reported income, asset-depletion programs let lenders qualify the borrower based on the income that liquid assets could produce. This is a common solution for retirees and high-net-worth buyers in Aspen and Telluride.
Bank Statement Loans
For self-employed mountain buyers, bank statement programs use 12 or 24 months of deposits to verify income instead of tax returns. The rates are higher than conventional but the underwriting is realistic for business owners.
Portfolio Loans
Above $3M, portfolio lenders keep loans on their own balance sheet and can write to terms the agencies won't allow. That can include interest-only, longer-term ARMs, and unusual property types.
The Cross-Market Read
Three things travel across all three markets:
1. Cash Buyers Still Compete on Speed, Not Price
Cash isn't always king when prices are constrained. A financed offer with a pre-underwritten file and a 21-day close can still win against a slower cash buyer.
2. Insurance Matters as Much as Rate
Wildfire and replacement-cost premiums in mountain markets can shift the loan file. Get an insurance quote before the offer. See our recent post on the Colorado wildfire insurance mortgage guide for details.
3. Pre-Underwriting Beats Pre-Approval
A pre-approval is paperwork. A pre-underwritten file means the lender has already reviewed the borrower's income, assets, and credit, and the only remaining unknowns are the property and appraisal. That's a real competitive edge in inventory-constrained markets.
The Honest 2026 Mountain Market Summary
Aspen is constrained and quiet at the top. Vail is bifurcated. Telluride is still climbing on luxury, slower below it. None of those are "good market / bad market" calls. They are different setups, each with a different financing answer.
Looking at a Colorado mountain property in 2026? Talk to Cedar Home Loans. We work conforming, high-balance, jumbo, and portfolio loans across every major Colorado mountain market. Call (303) 549-5277 or start a pre-approval here.